
Connecting Stripe to QuickBooks Online sounds like it should take five minutes. Turn on the bank feed, watch the deposits come through, and you’re done. Then month-end rolls around, the numbers don’t match, and you’re trying to work out how a $3,847.92 payout turns into gross sales, processing fees, and a refund you completely forgot about.
There’s a reason those numbers don’t line up, and you can fix it. It starts with understanding what Stripe is actually sending, why the bank feed can’t break it down by itself, and which setup records your revenue, fees, and payouts in the right accounts. Once you’ve done that, month-end usually becomes a review of the numbers instead of a search for what went wrong.
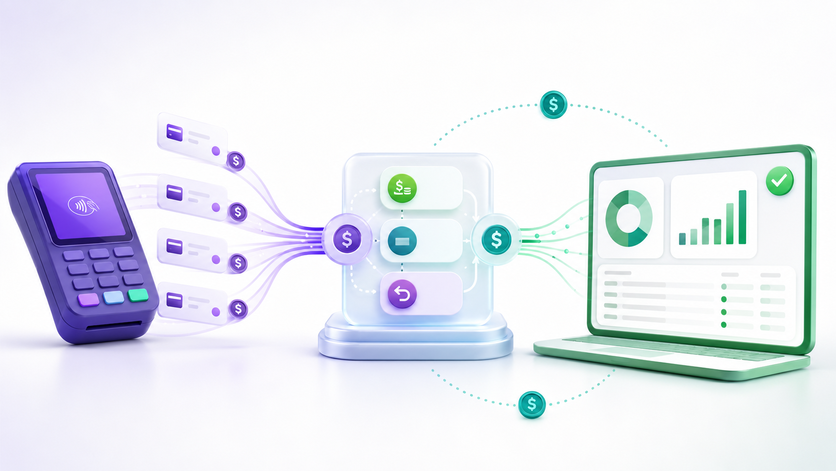
Most payment processors transfer a payment to your bank with only small deductions. Stripe works differently. Stripe works differently. It collects charges throughout the day, keeps them in a pending balance, deducts processing fees and any refunds, and then sends you the net amount. Sometimes that happens two days later. Sometimes it takes a week. Your bank only sees a single deposit, while your Stripe dashboard shows the dozens of transactions behind it.
To connect Stripe and QuickBooks Online properly, three pieces need to be recorded correctly: gross sales, the fees Stripe deducts, and the net payout that reaches your bank. That’s what a Stripe QuickBooks integration is meant to do. Instead of recording only the net deposit from your bank, it tracks gross sales and fees separately. A clearing account makes that possible, and once you understand how it works, the rest of the process usually makes much more sense.
A clearing account is a temporary holding account, usually set up in QuickBooks Online as an “Other Current Asset.” It bridges the gap between your sales activity and what eventually appears on your bank statement. Under US GAAP, and in day-to-day accounting practice, it’s the standard way to handle Stripe transactions. The process follows three steps:
When everything has been recorded correctly, the clearing account returns to zero at the end of each payout period, your revenue reflects the full amount you earned, and your Stripe fees appear in the expense accounts where an accountant would expect to find them. If the balance doesn’t return to zero and starts carrying forward from one payout to the next, it’s usually an early sign that something in the process has been recorded incorrectly.
Fees and refunds should each have their own account in your chart of accounts. Stripe’s processing fees are usually recorded as an expense, although some businesses classify them as a cost of goods sold. Refunds are generally recorded as contra-revenue so they reduce sales instead of increasing your expense totals.
Chargebacks need a little more attention. When a dispute is opened, Stripe deducts both the disputed amount and a dispute fee. If you later win the dispute, Stripe reverses both transactions. Your accounting records should reflect those reversals too, so you don’t leave a recovered payment or fee recorded as a permanent expense.
A bank feed can’t capture that level of detail. It only sees that a deposit or withdrawal took place. It has no way to tell whether the amount included dozens of customer payments, a partial refund, or a chargeback fee.
There’s no single setup for every business. The best choice depends on how many transactions you process and how much complexity you need to handle. The same decision applies to any payment processor that pays out a net amount. If you also accept PayPal, for example, the accounting logic behind a QuickBooks PayPal integration is much the same. The main difference is that PayPal often deducts its fee from each transaction instead of taking it out of a combined payout. Here’s what each option involves.
With this approach, you connect your business bank account to QuickBooks Online, and the bank feed imports each Stripe payout after it clears. There’s no additional software to set up and no subscription to pay for. The downside is that the bank feed only sees the final deposit. A $971 payout appears as $971, with no indication that it came from $1,000 in sales after $29 in Stripe fees.
If you want accurate books, you’ll need to split every deposit into gross sales, processing fees, refunds, and any other adjustments yourself, using your Stripe dashboard as the reference. That removes much of the time you’d hoped to save.
If you use this method, don’t accept QuickBooks’ suggested category for a Stripe deposit without checking it. It typically defaults to “Sales,” which records the net payout as revenue and often creates extra cleanup work at tax time. For a consultant processing a handful of payments each month, that may be manageable. As transaction volume grows, it quickly becomes difficult to keep up.
This method involves using Stripe’s payout CSV to record gross sales in a clearing account, posting processing fees and refunds as separate entries, and transferring the net payout out of the clearing account once it reaches your bank. If everything has been recorded correctly, the clearing account returns to zero at the end of each payout cycle. The result is accurate books and complete control, without paying for additional software.
The amount of work grows with your transaction volume. Recording around 20 charges a month usually takes only a few minutes. At 200 transactions, it can easily fill an afternoon for a bookkeeper. At 2,000, it becomes close to a full-time job, and mistakes become much more likely as the workload grows. That’s also when many businesses start looking for shortcuts, and the most common one is the one you should avoid.
When manual entry no longer keeps up with your transaction volume, a sync tool can read your Stripe data and record each charge, fee, refund, dispute, and payout in QuickBooks automatically. This is the approach many growing ecommerce and SaaS businesses end up using because reconciling bank deposits against the transactions processed in Stripe is often one of the most time-consuming parts of the month-end close.
Synder is one example. It’s an accounting automation tool that syncs financial data from more than 30 platforms into QuickBooks Online, QuickBooks Desktop, Xero, and other accounting systems, so the same setup also works for a Stripe Xero integration if that’s where you keep your books. For Stripe, it records sales, refunds, payouts, and processing fees as either individual transactions or summarized entries by period or payout. Its Transaction Reconciliation feature compares payment platform data with your accounting records, and subscription businesses can also use it to recognize deferred revenue under ASC 606 when customers pay upfront for services delivered over time.
If you just want a quick comparison, here’s how the three approaches differ in terms of cost, effort, and the situations they’re best suited for.
| Method | How it works | Best for | Watch out for |
| Native bank feed | QuickBooks imports the net Stripe payout from your connected bank account | Service businesses and low transaction volumes | Records only the net deposit, so fees and refunds need to be entered manually |
| Manual clearing account | You record gross sales, fees, and refunds yourself using Stripe’s payout CSV | Lower transaction volumes where you want full control without extra software | The workload increases quickly as transaction volume grows, making mistakes more likely |
| Third-party sync tool | Software imports Stripe data and records charges, fees, refunds, disputes, and payouts automatically | Growing businesses, high transaction volumes, multi-account setups, and accounting firms | Requires a subscription, and available features differ from one tool to another |
The best option depends on your transaction volume and how much time you want to spend on reconciliation each month. Reviews on G2 and Capterra often mention significant time savings for businesses processing large numbers of transactions, although some users say the initial setup and account mapping could take a bit of work.
Whichever approach you choose, it’s worth testing it on a single Stripe payout before importing your full transaction history. Check that the entries look right, the payout matches your bank deposit, and the clearing account returns to zero. If you’re only processing a small number of Stripe payments each month, the manual clearing account method may be all you need.
You won’t have a a built-in button that connects Stripe to QuickBooks Online. Instead, you’ll connect the two using one of the three methods above: the native bank feed, manual entry, or a third-party connector. The steps below describe the connector approach because it’s the one many growing businesses choose, although the same accounting logic applies to any method.
If your QuickBooks Online company already includes months of Stripe activity, many connectors can also import historical transactions so earlier periods follow the same clearing account structure as future ones. Spending a little time verifying the setup at the beginning usually prevents much larger reconciliation problems later.
A clearing account makes reconciliation much easier because it lets you compare each payout to the transactions behind it instead of a single bank deposit. The most reliable approach is to reconcile by payout rather than by day. Stripe provides a CSV export showing every transaction included in each payout, and that’s the report you’ll want to work from. Match the gross sales, processing fees, and refunds in the export to the entries in your clearing account, then confirm that the net payout matches the deposit in your bank account.
Here’s a simple example. A payout of $3,847.92 appears in your bank account on Tuesday. That payout includes $4,000 in gross sales, $145 in Stripe fees, and a $7.08 refund. If you record the deposit as a single sales entry, your revenue ends up understated by about $152, the processing fees never appear as an expense, and the refund isn’t recorded correctly. Recording each component through the clearing account keeps every amount in the right place and brings the account balance back to zero.
One habit makes reconciliation much more reliable: match the individual transactions within each payout instead of comparing the net payout with your sales total. The payout amount can match even when the gross sales, fees, or refunds have been recorded incorrectly. Reviewing each component helps you catch a miscoded fee or a missing refund before it carries through to your financial statements.
Most Stripe bookkeeping problems come down to one mistake: recording the net payout as revenue. It’s an easy mistake to make because that’s exactly what the bank feed encourages if you accept its default categorization. Over time, it’s also one of the main reasons Stripe and QuickBooks Online stop matching.
The gap between gross sales and the net payout is what causes most reconciliation problems. Stripe’s standard pricing is 2.9% + $0.30 per online card transaction, so a $1,000 sale usually reaches your bank as about $971. If you record that $971 as revenue, your books immediately start drifting off course. Gross sales are understated, the processing fee isn’t recorded as an expense, and your profit margins become less accurate. Keep recording payouts this way each month, and your tax preparer may end up correcting a full year’s worth of entries. The same issue comes up with most payment processors that deposit net amounts, so it’s a good habit to avoid from the beginning.
It’s easy to underestimate how much time this creates. Ledge’s 2025 Month-End Close Benchmarks report found that cash reconciliation alone takes between 20 and 50 hours a month for many finance teams, and half of those teams still need six or more business days to close their books. For businesses processing a steady stream of Stripe payments, a good portion of that time goes into breaking down payouts that appear in the bank feed as a single deposit with no explanation of what’s behind it.
The right approach depends on two things: how many Stripe transactions you process and how much accounting detail comes with them. A manual clearing account works well at lower volumes and gives you complete control over every entry. As transaction volume grows, or as fees, refunds, disputes, and multiple currencies become part of your day-to-day bookkeeping, automation usually becomes the more practical option.
No matter which method you choose, two habits make a big difference. Process every payout through a clearing account so gross sales and fees are recorded separately, and reconcile your Stripe activity by payout on a regular schedule, ideally each week. Keeping up with those checks makes it much easier to catch small discrepancies before they turn into a much larger cleanup at year-end.
Do I need Stripe if I have QuickBooks?
Yes. Stripe and QuickBooks do different jobs. Stripe processes card payments, handles payment networks, and manages disputes. QuickBooks records those transactions and turns them into financial reports. QuickBooks can’t process customer payments, and Stripe isn’t designed to manage your accounting, so many businesses use them together.
Is Stripe part of QuickBooks?
No. Stripe and QuickBooks are separate products from different companies. They don’t include a built-in one-click connection, so you’ll need to connect them using the bank feed, manual clearing account entries, or a third-party sync tool.
How does Stripe work with QuickBooks?
Stripe sends your bank a single net payout after deducting processing fees and refunds, while the details of every payment remain in Stripe. To keep your books accurate, record gross sales, fees, and refunds separately through a clearing account, then match the net payout to the bank deposit so the clearing account returns to zero.
How can you integrate Stripe and QuickBooks?
Start by choosing the connection method that fits your transaction volume. Then connect your Stripe and QuickBooks accounts, map your Stripe activity to the appropriate accounts in your chart of accounts, choose between per-transaction and summary sync, and test everything with a single payout before syncing the rest of your data. The step-by-step section above explains each part of the process.
Can I just use the QuickBooks bank feed for Stripe?
Yes, although it’s usually practical only if you’re processing a small number of Stripe payments each month. The bank feed imports the net deposit but doesn’t show the individual sales, processing fees, refunds, or other adjustments behind it. You’ll need to add those manually if you want accurate financial records, and recording the net deposit as revenue can create bookkeeping problems that build up over time.


